
Payment Decoded - Schemes: The Global Payment Networks Behind Every Transaction
When you pay with a card, be it Visa, Mastercard, American Express, or UnionPay, there’s a powerful network working silently in the background to ensure the transaction is authorized, secure, and completed in seconds. In fact, these networks processed an estimated 791 billion credit card transactions worldwide in 2024. Known as Schemes, they form the backbone of the global card payment ecosystem.
What Is a Payment Scheme?
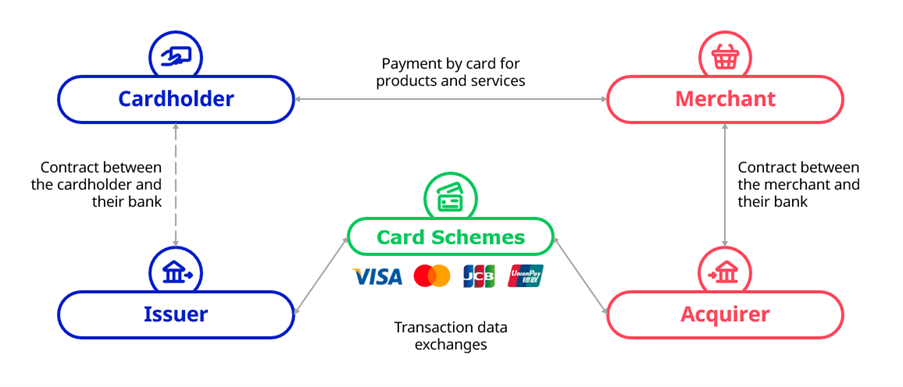
A Scheme is a set of rules, standards, and technology that connects issuers (the banks that give you your card) with acquirers (the banks or payment providers that enable merchants to accept card payments).
In simple terms, schemes are the middle layer that ensures your card works the same way across the world, whether you’re buying a coffee in Paris, booking a hotel in Tokyo, or shopping online in New York.
They define:

How data is transmitted and secured

Interchange fees, settlement timelines, dispute handling

A consistent user experience across millions of merchants
How Schemes Work in the Payment Chain
When a customer pays with a Visa or Mastercard, here’s what happens:
- The POS terminal or e-commerce platform captures the card details.
-
The transaction request goes to the Acquirer, which routes it through the Scheme.
-
The Scheme securely passes the request to the Issuer for approval.
-
The Issuer checks available funds, fraud risk, and security protocols.
-
The approval flows back through the Scheme and Acquirer to the merchant’s POS.
-
Funds are settled later between Issuer, Acquirer, and Merchant under Scheme rules.
All of this happens in milliseconds but only works because the Scheme provides the “common language” and governance.
Why Schemes Matter
Schemes ensure interoperability. Without them, each bank would need direct connections with every other bank worldwide, which would be inefficient and costly. Instead, a Scheme acts as a universal switchboard, guaranteeing that a card from one bank works at another bank’s terminal anywhere in the world.
For Merchants, Schemes Mean:


For Consumers, Schemes Mean:


The Evolving Role of Schemes
The payments ecosystem is shifting rapidly, shaped by new technologies, local payment methods, and stricter regulations. Schemes continue to play a central role, but their function is changing:
- Regulatory pressure: Authorities in many regions (e.g. PSD2 in Europe) impose stricter requirements on fees, security, and transparency, directly impacting scheme operations.
-
Competition from alternative payment methods: Local networks, account-to-account payments, and digital wallets are challenging the dominance of global card schemes, especially in emerging markets. This is why for Tax Free Shopping, you need to work with a provider that can support you on this topic like Global Blue.
-
Innovation at the edges: Schemes are adapting by updating security standards (like tokenization), ensuring compatibility with mobile payments, and aligning with new authentication requirements.
In this environment, schemes act less as disruptors and more as stabilizers, maintaining global interoperability while responding to external pressures.
FAQ
A Scheme sets the rules and network connections, while an Acquirer is the merchant’s bank or payment partner that connects to the Scheme.
No. They don’t issue cards or provide accounts. They are technology networks that connect issuing banks and acquiring banks.
Most markets support Visa and Mastercard, but some regions also have strong domestic schemes like RuPay (India) or Cartes Bancaires (France).
They earn revenue from network fees charged to issuers and acquirers for each transaction processed.
Get in Touch
Let's connect and discover the ideal way that we can support your needs.


